Rupesh N. Chavan Gen Z UPI Payments & Wealth 2026

The count
you keep.
Safe to spend.

A payments and wealth app for the 22-year-old who transacts fifteen times a day. Built on UPI rails, with the attention economy taken out of it.
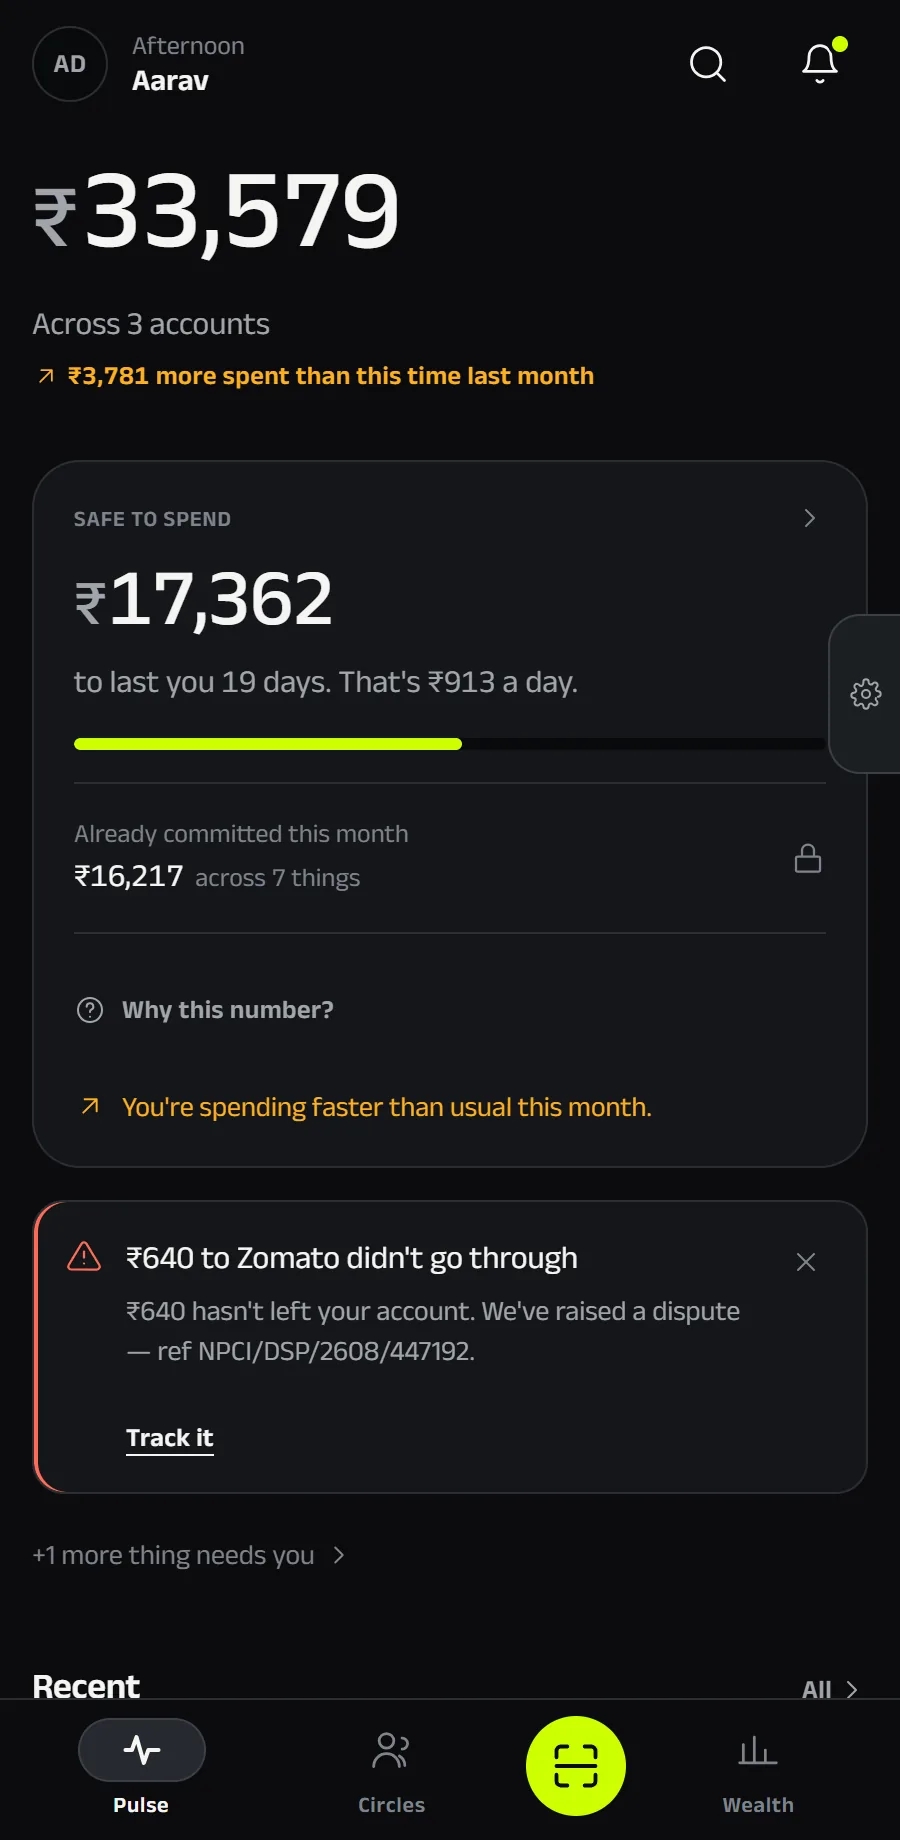
ANKA · the Pulse home screen showing a Safe to Spend daily figure
Project Overview

A payments app that refuses to sell your attention.

Real-time spendable clarity, built on UPI rails

ANKA is a Gen Z-first payments and wealth mobile application for India, built on UPI rails. It re-engineers financial anxiety into real-time spendable clarity. "Safe to Spend", with automated N-1 group expense debt resolution and a zero-ads dark design system in Material 3 Expressive and Jetpack Compose.

Three things were fixed before anything was drawn: the home screen would carry one number rather than forty tiles, group debt would resolve on the ledger instead of in a group chat, and the business would never be allowed to earn a rupee from a user's attention.

RoleLead Product & Systems Designer
Timeline2026
CategoryFintech · Consumer UPI
PlatformAndroid · Jetpack Compose · Material 3
0
Ads or scratch cards
4
Permanent tabs
N‑1
Group settlement
100%
Tabular figures
The Challenge

The incumbents built a bazaar. Gen Z needed a tally.

Four problems the category had stopped treating as problems

PhonePe, Google Pay and Paytm process billions of monthly UPI transfers, but every incumbent optimises for the transaction while monetising user attention. Home screens are packed with 40-tile bazaars, scratch cards and ad banners. Meanwhile 22-year-old Indians transact eight to fifteen times daily and carry constant low-grade money anxiety.

01
40-tile bazaar clutter
Incumbents overload screens with credit offers, commerce tiles and scratch cards that feel like a noisy bus station.
02
Money anxiety and false balances
Static bank balances mislead users into spending money that is already committed to upcoming bills and rent.
03
Awkward group debt follow-ups
Splitting group bills forces manual math and pairwise transfers at N² complexity, causing social friction.
04
Single-PSP outage failures
Single-bank PSP outages account for the majority of one-star payment app reviews in India.
The Solutions

Two features nobody else has.

Plus one constraint treated as a feature

ANKA introduces two product wedges designed to eliminate financial anxiety and simplify social payment workflows, and a third decision, about navigation, that only looks like a feature once you have used the alternatives for a year.

Innovation 01
Safe to Spend engine
Problem. Current apps show static account balances, misleading users into overspending before bills hit.
Approach. Calculate upcoming committed outflows, rent, SIPs, EMIs, and divide remaining cash by days left in the month.
Output. "₹19,240 to last you 11 days. That's ₹1,749 a day."
A forward-looking daily spend limit changes financial behaviour from anxiety-driven guessing to clear, daily boundaries.
Innovation 02
Circles, N-1 debt resolution
Problem. Group bill apps require manual calculation and multiple pairwise transfers across members.
Approach. Pay the merchant, swipe the row, and requests go out. Multi-party debts automatically resolve in N-1 transfers.
Output. Group debts settle in single-tap transfers without awkward reminders.
Math is solved at the ledger level, removing social awkwardness and reducing transaction friction.
Innovation 03
Four permanent tabs
Problem. Incumbent navigation changes constantly as new monetisation features are added.
Approach. A permanent four-tab architecture, Pulse, Circles, Pay, Wealth, organised by time relationship to money.
Output. Zero fifth-tab expansion. A fifth tab is treated as a product failure.
Organising by the user's mental model ensures predictability and long-term brand trust.
UI Overview

Four tabs carry the whole product.

Each one replaces a fragmented financial task with immediate clarity
Pulse

Present state.

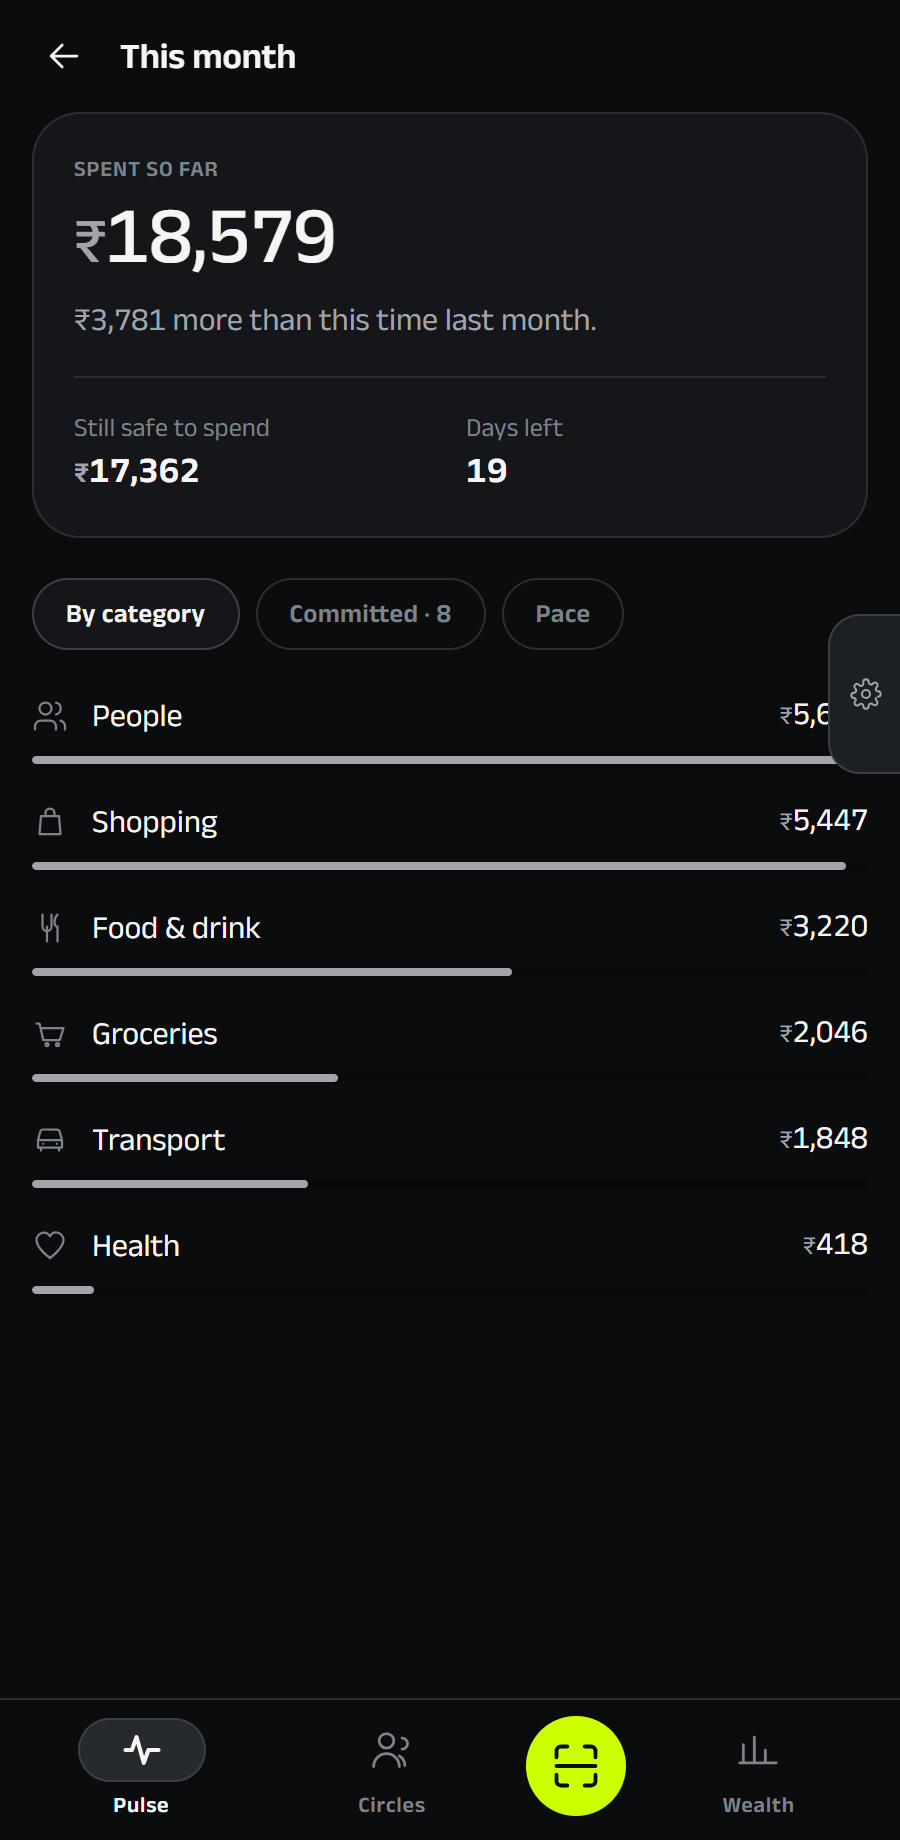
The primary home surface, carrying the Safe to Spend daily limit, committed outflows and a live payment feed.

Problem
Users don't know how much money is genuinely spendable today.
Approach
A single hero spendable number, calculated against upcoming commitments.
For the user
Instant daily clarity; the overspending anxiety goes away.
For the business
A daily habit without artificial engagement gimmicks.
ANKA Pulse · the home dashboard with the Safe to Spend figure
Circles

The social ledger.

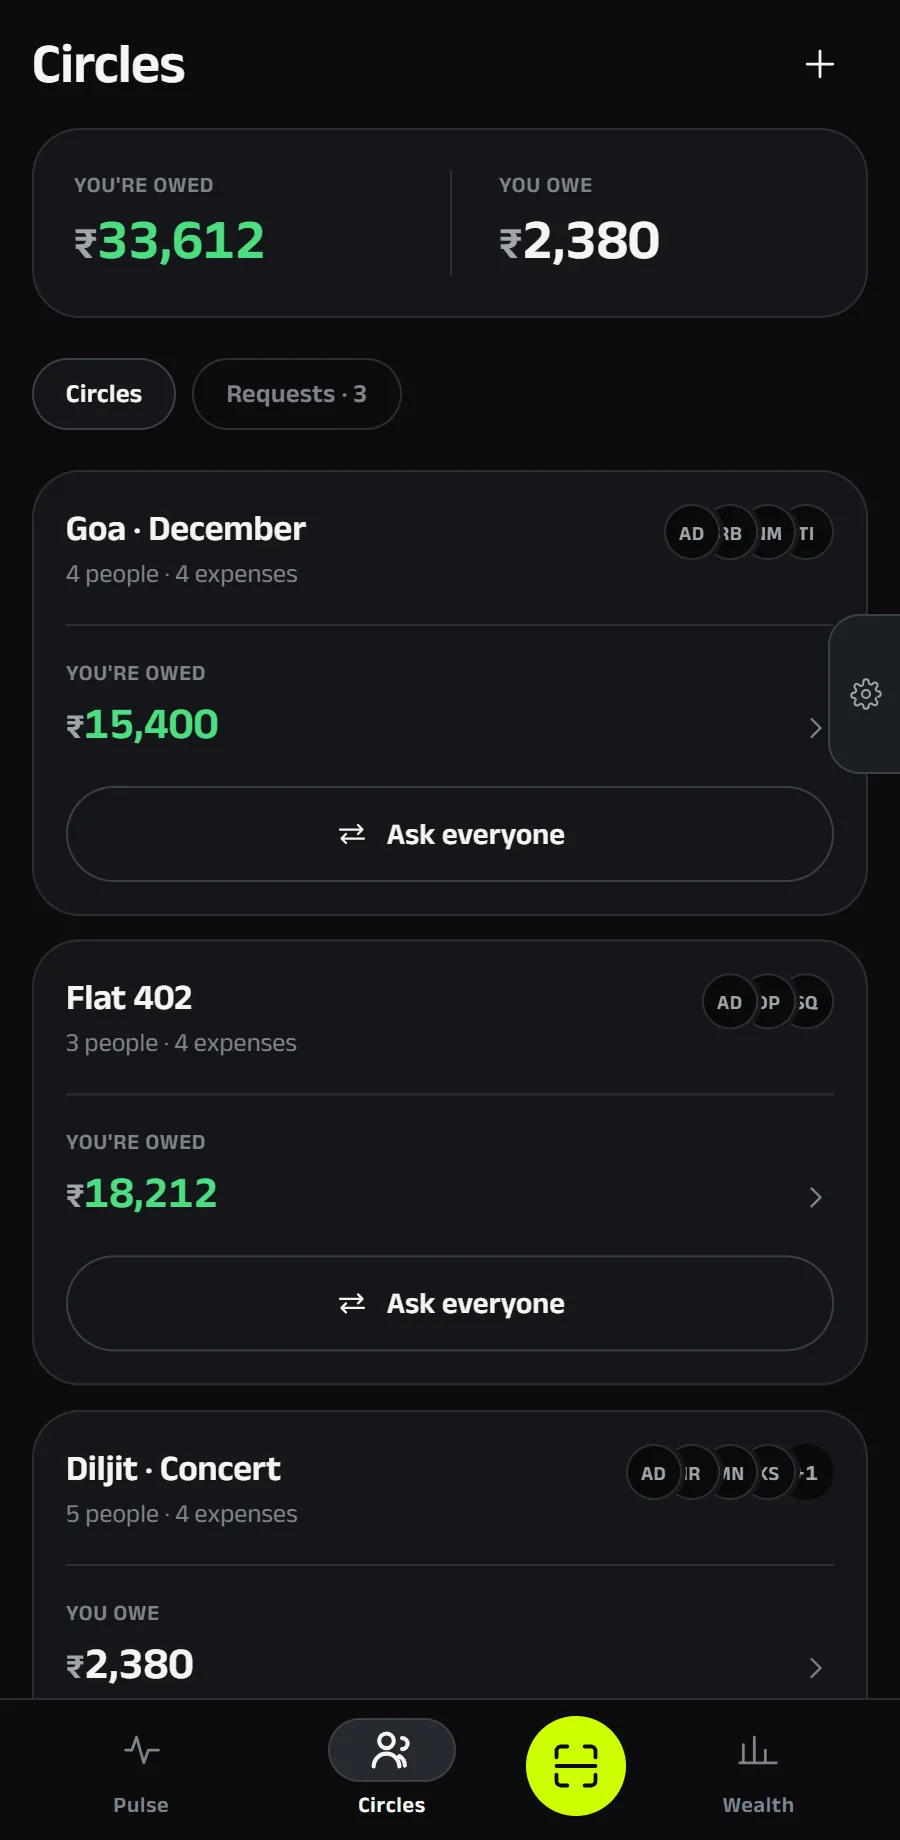
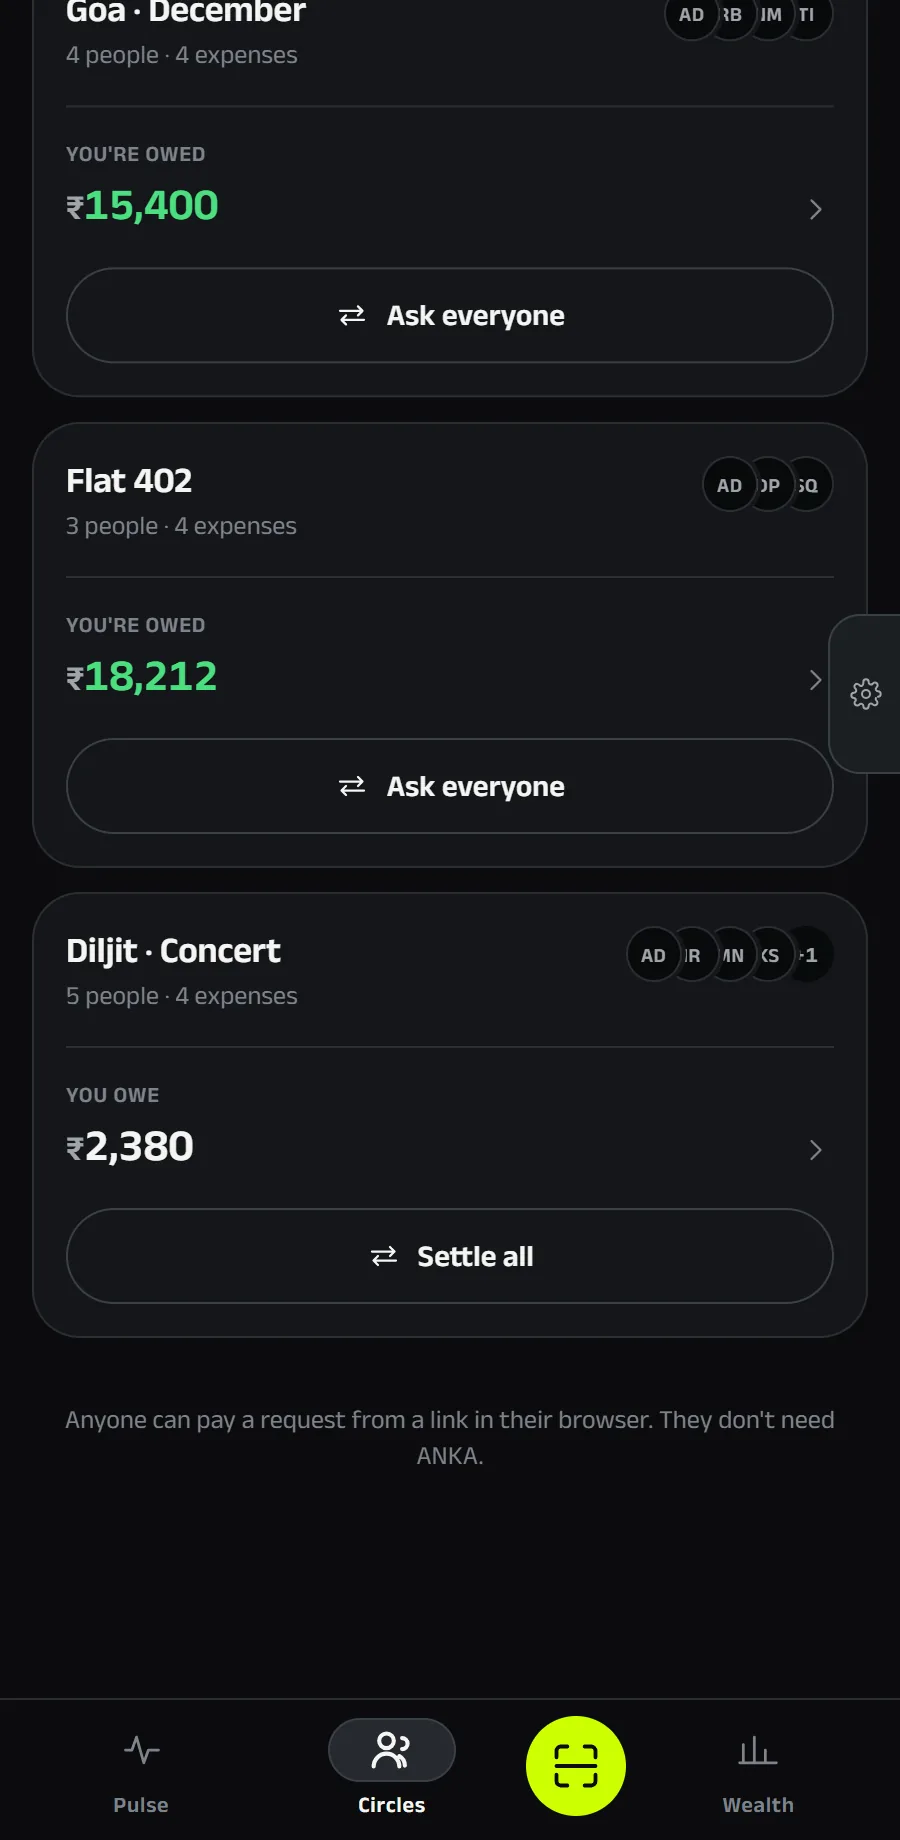
Group expense tracking, trip tallies, flatmate bills, with automated N-1 debt resolution.

Problem
Splitting bills requires awkward manual math and multiple individual transfers.
Approach
A single payment swipe triggers instant requests; the ledger computes N-1 transfers.
For the user
Debts settle without anyone having to send a reminder.
For the business
Viral acquisition through multi-party group invites.
ANKA Circles · group expenses and single-tap debt resolution
Pay

The frictionless rail.

A high-speed camera QR scanner, a recent-contacts tray, and a custom tactile amount keypad.
Problem
Camera initialisation lag and slow keypad entry cause merchant checkout friction.
Approach
Hardware-accelerated QR scanning and a tabular keypad with spring haptics.
For the user
Sub-second launch to completed payment.
For the business
Maximises successful UPI checkout completions.
ANKA Pay · the tactile amount keypad with rolling tabular numerals
Wealth

Future state.

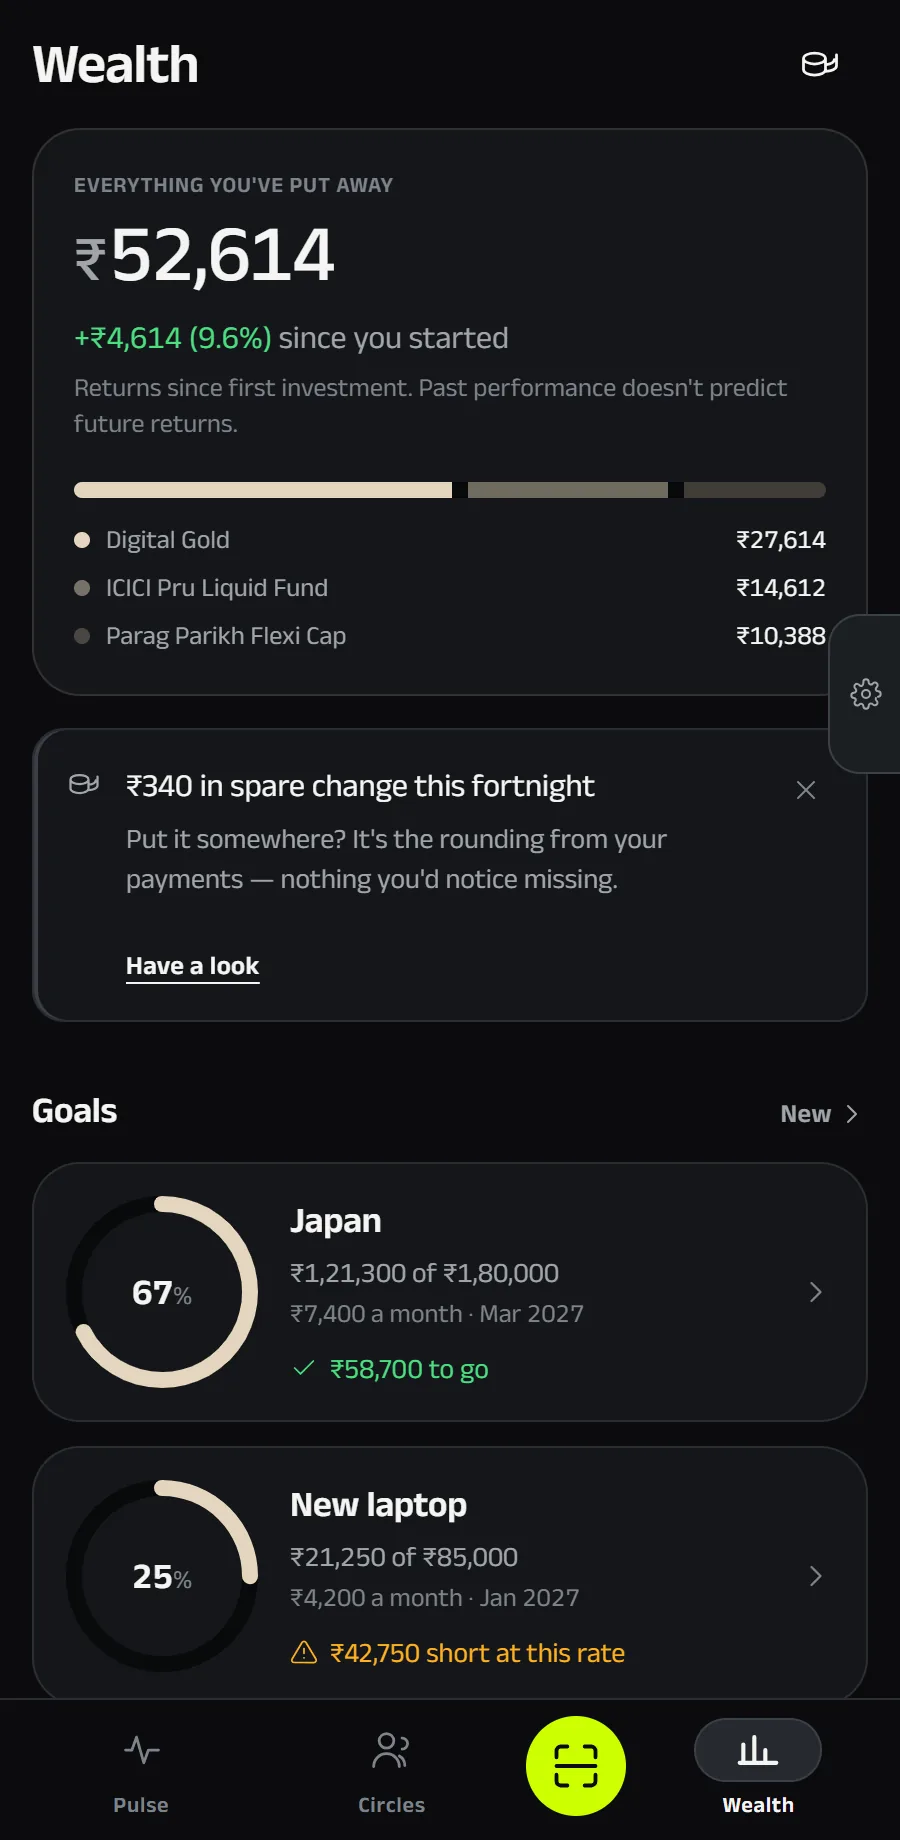
Goal-based micro-SIPs, consolidated net worth, inflation tracking and passive accumulation.
Problem
Gen Z avoids complex investment platforms with high-pressure sales jargon.
Approach
Simple goal rings, automated roundups and transparent AUM fee disclosure.
For the user
Long-term wealth without the financial jargon.
For the business
High-margin AUM revenue with no advertising dependency.
ANKA Wealth · goal rings, micro-SIPs and a net worth tracker
Design System · "Tally"

Volt on Ink. Dark by default.

A spice, never a sauce · 5 to 8% of any screen

Nobody in Indian fintech owns Volt on Ink. PhonePe is purple, Paytm and Airpay are blue, Google Pay is multi-colour on white. Volt covers strictly 5 to 8% of any screen, a high-contrast spice, never an overwhelming sauce.

Volt accent#CCFF00
Ink substrate#0B0C0E
Dark charcoal#16181F
Volt glow#E6FF66
Secondary#99A1B3
Coral alert#FF6633
Anek
One variable family covering ten Indian scripts and Latin, so a Marathi balance and an English one are set in the same voice.
₹1,749.00
Tabular figures are mandatory on every balance and ledger row, tnum everywhere, so columns never jitter as digits change.
Money has mass
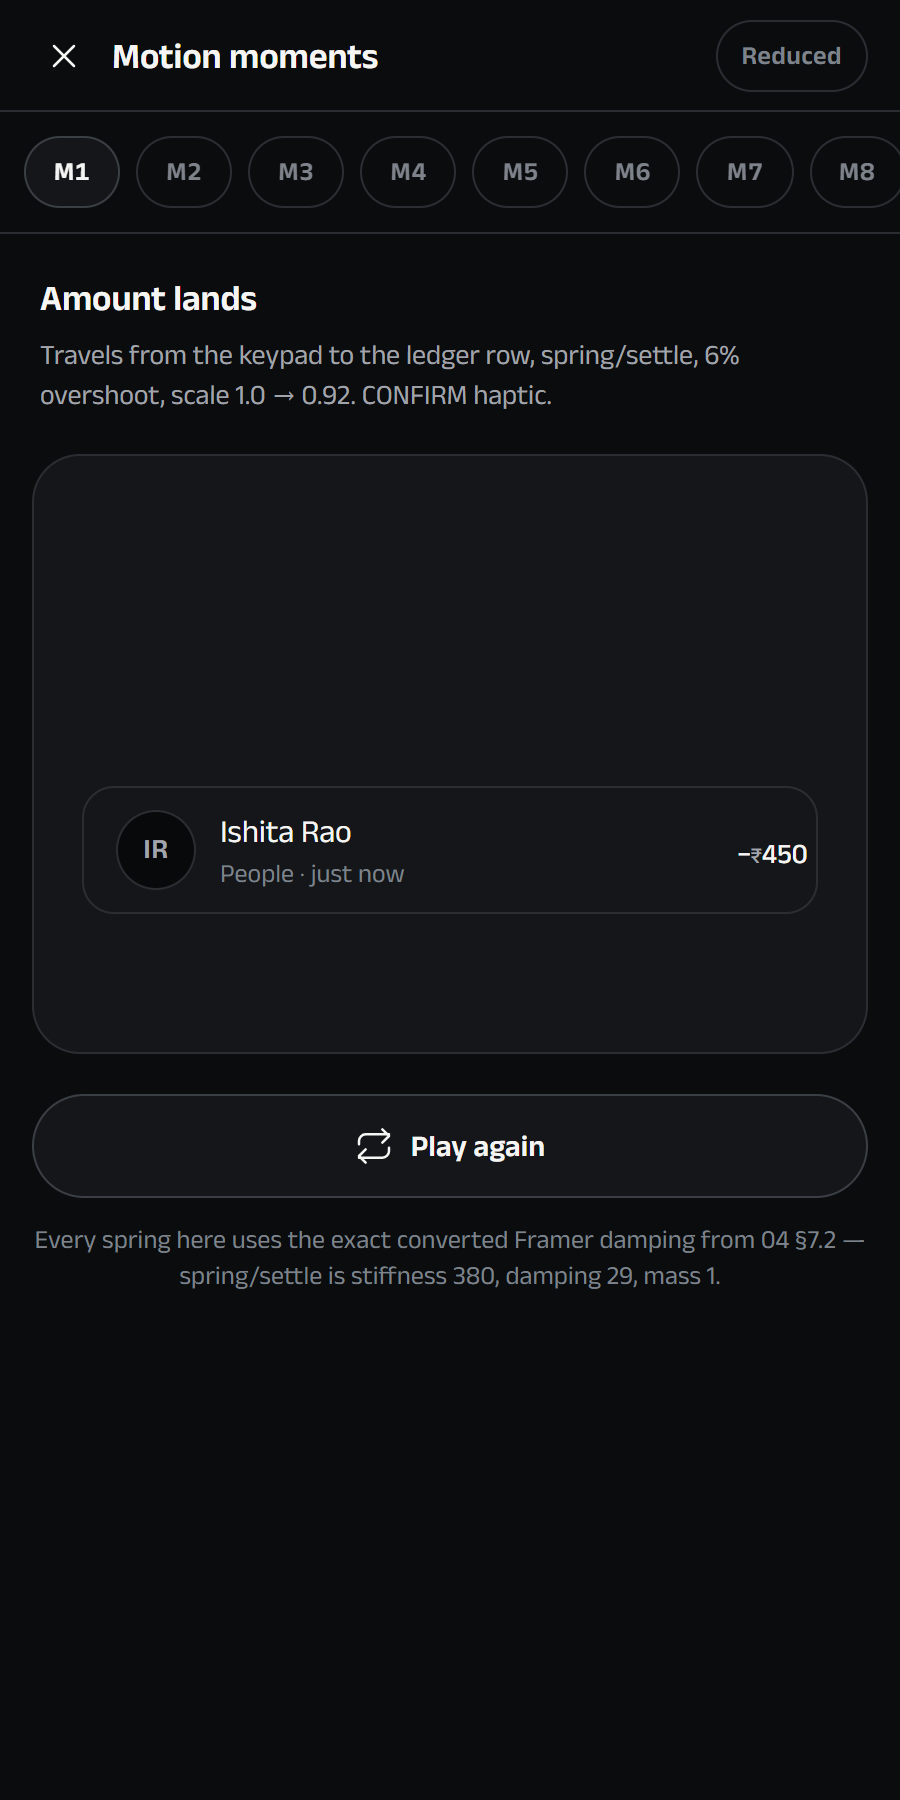
Spring physics, stiffness and damping, rather than duration-and-easing curves. Completed amounts land on ledger rows with real overshoot.
Material 3 Expressive substrate
Built on M3 Expressive Compose components, custom-themed with Volt/Ink tokens and twelve custom financial primitives.
Zero-ad brand constraint
A founder-level veto on sponsored tiles, scratch cards and third-party ads. Revenue comes strictly from AUM, credit interchange and MDR.
Architecture as trust
Double-entry ledgers and multi-PSP failover redundancy, so that when a payment is made it works every single time.
Screens

Every surface, end to end.

Click any screen to open it full size
Outcomes

Designed for trust. Engineered for speed.

Consumer fintech without dark patterns

ANKA proves that consumer fintech does not require dark patterns or attention-selling to build a sustainable business. The system prioritises user clarity over commercial noise.

0
Ads or scratch cards
Zero attention-monetisation clutter on any surface.
N‑1
Transfer efficiency
Automated group debt settlement, reducing pairwise friction.
100%
Tabular numeral alignment
Pixel-perfect numeric columns with no animation jitter.
4
Permanent tabs
Predictable navigation, organised by time relationship to money.
Key Learnings

What this project taught me.

01
Clarity reduces financial anxiety
Showing a static balance makes users nervous about hidden upcoming bills. Calculating genuinely disposable cash turns that anxiety into confidence.
02
Numerals are the primary content
Financial UI lives and dies by numeric legibility. Enforcing tnum tabular figures across ten Indian scripts in Anek was non-negotiable.
03
Restraint builds premium brand equity
Volt at 5-8% density on Ink created an identity that instantly separates ANKA from the blue and purple incumbents.
04
Architecture dictates user trust
Double-entry ledgers and multi-PSP failover redundancy are what make a payment work reliably every single time.
Reflection
"The single constraint that defined ANKA was refusing to monetise attention. Every incumbent app in India eventually turns into a 40-tile bazaar of scratch cards, credit ads and sponsored banners. By keeping the surface dark, permanent and focused strictly on Safe to Spend clarity, ANKA gives Gen Z something money apps forgot to offer, peace of mind."
Rupesh Chavan, Lead Product & Systems Designer
DesignerRupesh N. Chavan
Year2026
ProductANKA, Safe to Spend
DisciplinesProduct Design · Design Systems · Fintech UX
Explore more